Exports
Usance Letter of Credit: Payment Security for Exporters and 5 Points to Check
Written by Enes Ünal, Export and Business Development Lead
 Reviewed by Sertaç Öztürkcan, Co-Founder
- Related service Export Consulting
- The basics What is exporting?
Contents4 sections
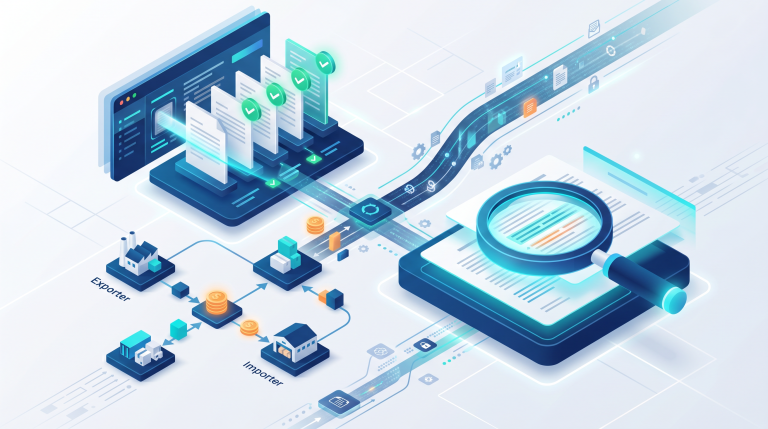
A usance letter of credit (deferred payment L/C) is an L/C under which the bank pays the exporter a set period after the documents are presented, not on presentation as with a sight L/C. The buyer gets time to pay, and the issuing bank guarantees the payment. Once compliant documents are presented, the bank is bound and pays at maturity, so the buyer’s insolvency or objection cannot stop it.

Why Turkish exporters choose usance letters of credit
Many of Türkiye’s export markets, particularly in the Middle East, Africa and Central Asia, are ones where buyers expect deferred payment. Exporters who insist on cash in advance or payment at sight (sight L/C) lose ground to competitors there. A usance L/C lets you offer the buyer flexibility without giving up the bank’s security.
For companies that want to keep a buyer relationship going without moving to fully unsecured open account terms, a usance L/C is a valuable middle ground.
Key elements of a usance letter of credit
- Tenor: usually 30, 60, 90 or 180 days from the date of presentation or the bill of lading date.
- Issuing bank’s obligation: once the documents are found compliant, the bank confirms in writing and pays at maturity.
- Confirmation: when a correspondent bank also takes on the payment undertaking, the exporter has the security of both the issuing and the confirming bank. In high-risk countries, this is essential.
- Document compliance: the documents must match the L/C terms exactly; otherwise the exporter loses the bank’s security.
Usance L/C vs sight L/C and other payment terms: a comparison
| L/C type | Payment time | Bank security | Exporter risk |
|---|---|---|---|
| Sight L/C | On presentation of documents | High | Low |
| Usance L/C (deferred payment) | A set number of days after presentation | High | Low to medium |
| Acceptance L/C | When the bill of exchange matures | Medium to high | Medium |
| Documents against payment (D/P) | On delivery of documents | None (the bank only handles documents) | Medium |
| Open account | As agreed | No | High |

5 points to check with a usance letter of credit
- Review the L/C as soon as it is issued: check every term against the sales contract under UCP 600, and fix any mismatch before the goods are loaded.
- Negotiate confirmation: in markets with country risk especially, agree in the contract who pays the confirmation fee.
- Check when the tenor starts: 90 days from the bill of lading date and 90 days from presentation are not the same thing for your cash flow.
- Be ready for discrepancies: one faulty document suspends the bank’s obligation, so work closely with the carrier, the insurer and the customs broker.
- Consider discounting (forfaiting): if you need cash before maturity, a bank or forfaiting company can discount the receivable.
How FIX supports you through the L/C process
A usance letter of credit is a technical instrument, and in practice many stages, from buyer negotiation to document preparation, call for Export Consulting. At FIX, we support clients end to end, from checking that the L/C terms match the contract to choosing the confirming bank and managing the documents.
Payment security does not end with choosing the L/C. It works together with market analysis, buyer intelligence and the right contract structure, and managing all of that with data saves both time and budget.
For more on managing your export processes, see our Export and Business Development service.
The UCP 600 rules published by the International Chamber of Commerce are the core reference for the parties’ rights and obligations in letter of credit transactions.
Frequently asked questions
-
What is the difference between a usance L/C and an acceptance L/C?In a usance L/C, the payment obligation comes straight from the bank as a written undertaking…
In a usance L/C, the payment obligation comes straight from the bank as a written undertaking; no bill of exchange is drawn. In an acceptance L/C, the bank accepts a bill of exchange, which can then be discounted in the market. Both give the buyer time to pay, but the legal basis and the instrument differ.
-
What happens if the documents do not comply?If the documents do not match the L/C terms (a discrepancy), the bank suspends its payment…
If the documents do not match the L/C terms (a discrepancy), the bank suspends its payment obligation and notifies the exporter. The exporter can correct and re-present the documents, or ask the buyer to waive the discrepancies. That is why document preparation is so important.
-
What is the usance period for a letter of credit?In commercial practice, the tenor of a usance L/C is usually between 30 and 360 days.
In commercial practice, the tenor of a usance L/C is usually between 30 and 360 days. The upper limit depends on bank and country risk, and longer tenors usually mean a confirmation requirement and higher bank costs.
-
What if the exporter needs cash before maturity?The exporter can have the receivable discounted by a bank or a forfaiting company.
The exporter can have the receivable discounted by a bank or a forfaiting company. The discount cost is deducted from the amount due at maturity and the cash is paid upfront. Build that cost into your pricing from the start.
At FIX, we work with you at every stage, from negotiating L/C terms to checking document compliance. Get in touch and let’s secure your export payments together.